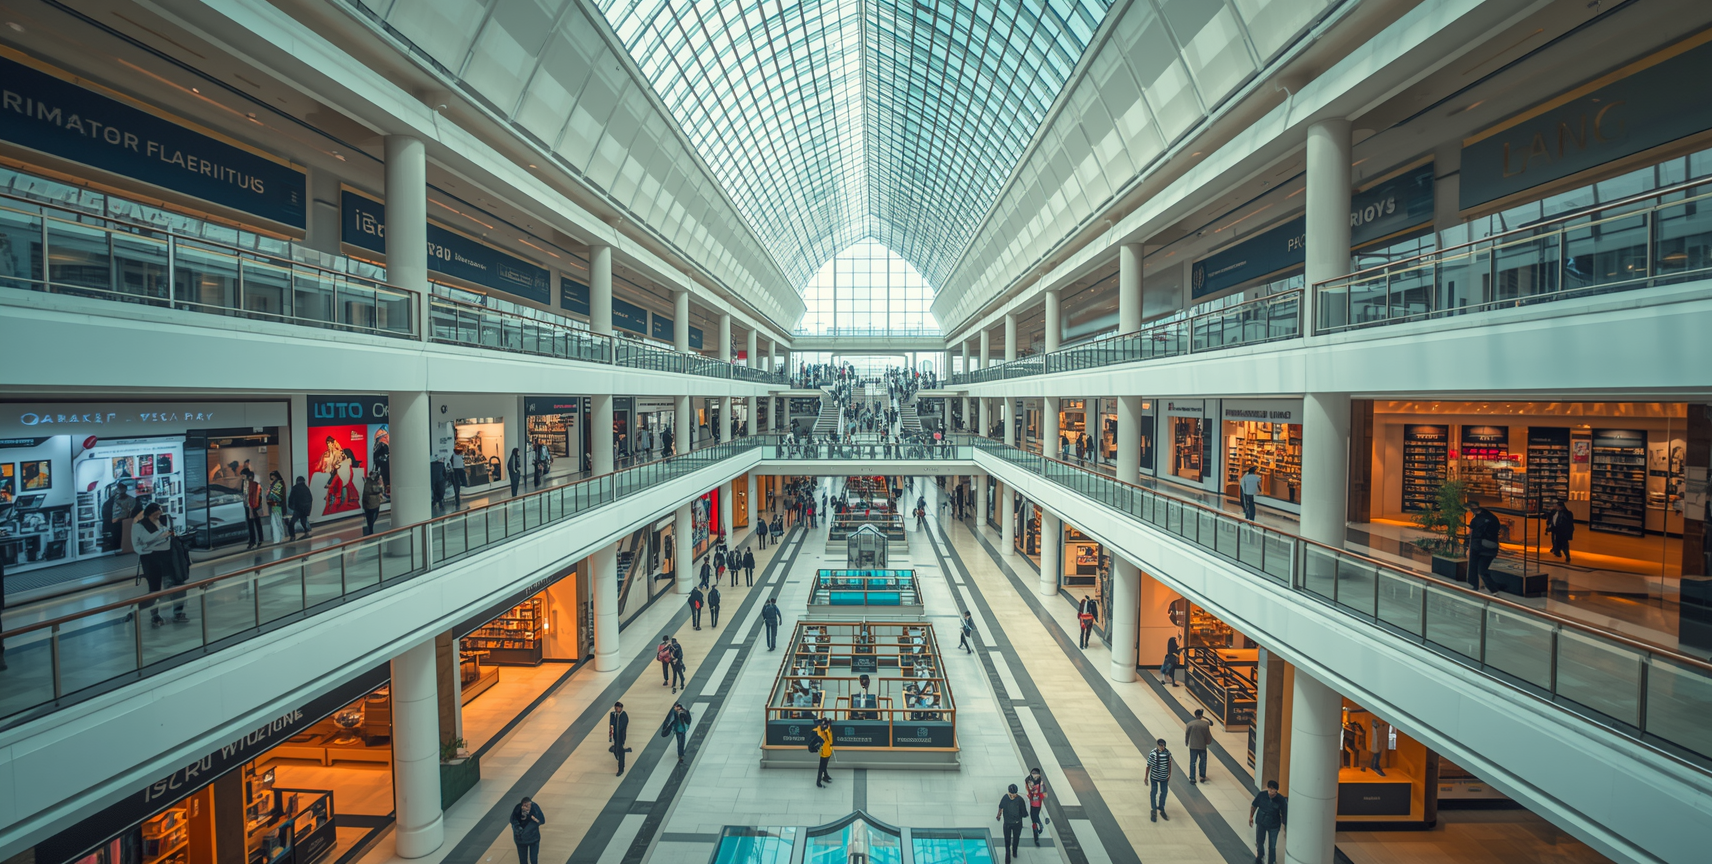
India’s premium retail real estate market is witnessing a sharp supply crunch, with top malls in the National Capital Region (NCR) operating at near full occupancy and Mumbai recording the steepest rental growth in the country, according to a new report by ANAROCK and Images Group.
The report, unveiled at the Phygital Retail Convention in Mumbai, highlights that vacancy levels in Grade A and A+ malls in NCR have dropped to just 0–2%, effectively indicating full occupancy in prime retail destinations. This tightening supply has triggered strong developer confidence, with nearly 19 million sq. ft. of new retail space planned in NCR between 2026 and 2031.
Mumbai’s retail market is also showing strong momentum. Leasing transactions across premium malls indicate a sharp 15–20% year-on-year rise in rentals, making it the fastest-growing retail rental market among India’s top cities. High-end malls such as Phoenix Palladium and Jio World Drive are commanding rentals as high as ₹777 per sq. ft. per month.
The surge in demand is being driven by aggressive expansion from international brands and entertainment anchors. Recent high-profile deals include Zara and Levi’s leasing space in Delhi malls and Foot Locker entering the Indian market through a major mall in Noida.
Across India’s top seven cities, more than 45 million sq. ft. of new retail supply is expected to be added between 2026 and 2031. Despite this pipeline, the report suggests that demand for high-quality retail spaces continues to outpace supply, especially in premium locations.
At the same time, the sector presents a massive investment opportunity. Based on current Grade A retail stock and capital values, India’s retail real estate market offers a potential investment window of $25–30 billion. Additionally, around 40–50 million sq. ft. of underperforming Grade B and C malls across major cities present redevelopment opportunities.
City-wise trends indicate a mixed but positive outlook. Bengaluru continues to maintain healthy occupancy levels with vacancy rates of 5–8% and stable rentals in the ₹200–250 per sq. ft. range. Hyderabad is emerging as a major supply hub with over 7 million sq. ft. expected by 2031, while Pune is seeing strong leasing activity driven by global brands like IKEA and Uniqlo.
Chennai’s retail market remains stable with moderate rentals, while Kolkata’s limited upcoming supply is expected to support existing rental levels.
A key emerging trend is the shift toward suburban retail development. In Mumbai, upcoming retail supply is concentrated in areas like Thane, Borivali, and Panvel, while Bengaluru’s growth is moving toward corridors such as Sarjapur Road. This reflects saturation in central business districts and rising demand in residential catchment areas.
The report also highlights evolving leasing structures, with nearly 74% of transactions now following hybrid revenue-sharing models and about 75% of leases signed for durations between three to seven years.
Overall, India’s retail real estate sector is entering a phase of strong growth, backed by rising consumption, limited premium supply, and increasing interest from institutional investors such as REITs, private equity firms, and sovereign wealth funds.
Also Read: Housing Prices Surge in 2024, Delhi NCR Leads with 31% Growth