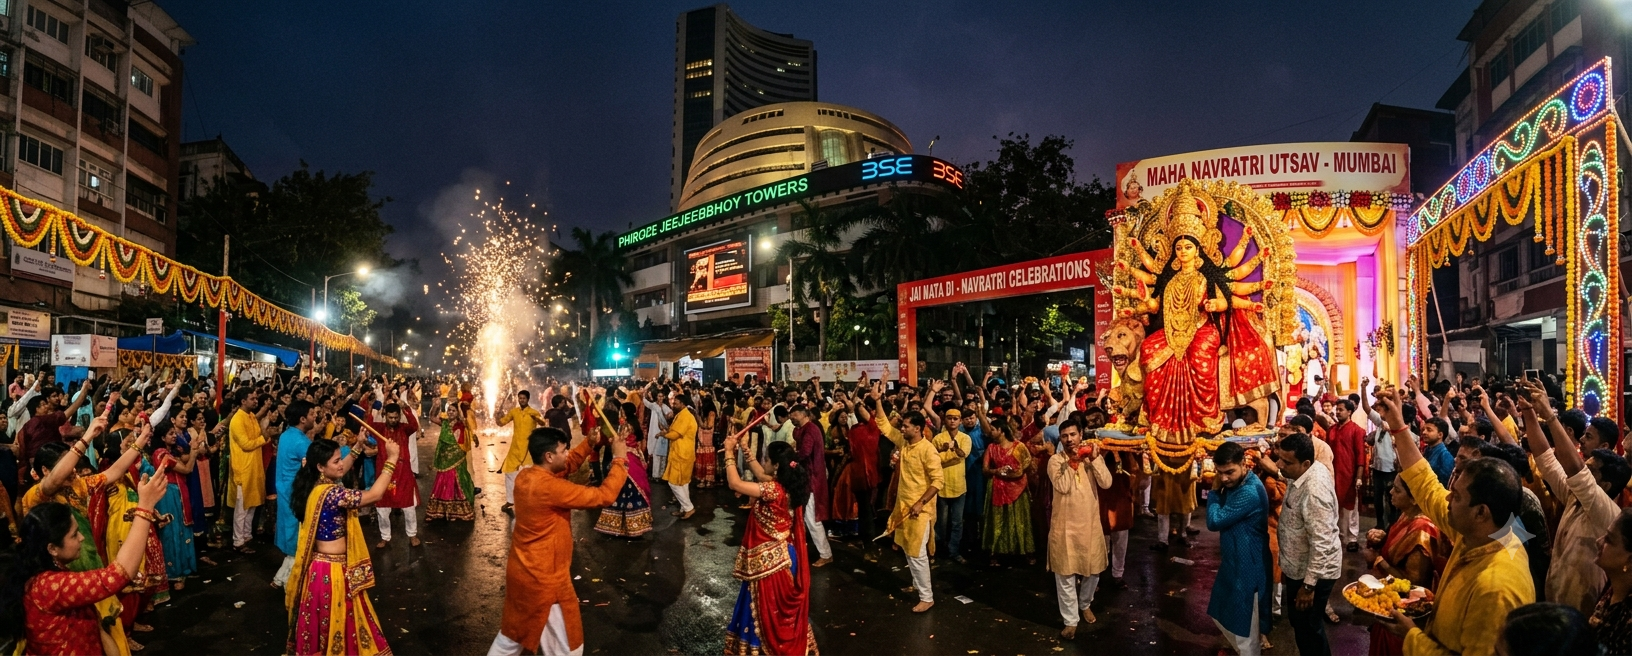
Two days after the RBI delivered India’s first repo rate hike since February 2023, the market is beginning to find its footing. The Sensex is up 700 points. The Nifty has crossed 22,450. Oil has softened in Asian trade. And India’s listed realty stocks — which had absorbed two consecutive sessions of selling pressure driven by the rate hike and crude above $102 — are opening Friday with the steadiness of a sector that has been here before. More importantly, Navratri begins tomorrow. The homebuyers who have been planning their festive season purchases through seven months of war, three weeks of market decline, and two days of rate hike shock are walking into developer sales offices on Saturday. That appointment does not move for a rate hike. And for the first time this week, the broader market’s mood is not working against it.
The Peg: The Rate Hike Shock Is Two Days Old. Navratri Is One Day Away.
The RBI’s 25 basis point hike to 5.50% on Wednesday October 7 — unanimous 6-0, stance shifted to calibrated tightening, rate cuts explicitly taken off the table — was the most consequential domestic monetary policy event the sector has faced since the 2025 easing cycle began. The market’s initial verdict was swift and severe. The Sensex lost 429 points on Wednesday. Thursday compounded the damage — the Sensex crashed a further 1,045 points to close at approximately 71,593. The Nifty fell to 22,231 — its lowest since April 2026. Nifty Realty was among the top two sectoral drags on both days.
But markets do not price the same information twice at the same intensity. Wednesday priced the surprise of the hike. Thursday priced the depth of the MPC’s hawkishness — the unanimous vote, the stance shift, the governor’s explicit “no rate cuts” guidance. By Friday, both of those pieces of information are in the price. The rate is at 5.50%. The stance is calibrated tightening. Home loan rates are rising by 25 basis points. Navratri buyers know this when they walk into developer offices tomorrow.
What is not yet in the price — and what Friday’s session is the first opportunity to begin pricing — is the festive season demand that opens tomorrow. The homebuyer in Thane who books a Lodha apartment on Saturday is making a decision that a 25 basis point rate increase has complicated at the margin but not cancelled. The family in Gurugram that walks into a DLF Privana sales office on Saturday morning has been saving for this purchase through seven months of Iran conflict. Their ₹75 lakh home loan EMI has gone up by approximately ₹1,200-1,500 a month. That is real and it matters. But for the buyer who has already committed emotionally and financially to a Navratri purchase, it adjusts the timeline rather than cancelling the decision.
The first Navratri booking figures — however preliminary, however informal — will begin emerging from developer channels through the weekend. Those numbers are what the market will be pricing from Monday onward. Friday is the last session before that data begins arriving.
How Realty Stocks Are Opening
Thursday’s closing Nifty Realty index level of approximately 795-810 — having fallen as one of Thursday’s two top sectoral drags — enters Friday’s session from the most depressed price level of Q3 FY27. The sector has now given back the entirety of the October recovery that Monday and Tuesday had built, and sits at levels last seen before the Hormuz joint statement had driven August’s relief rally.
DLF, the index’s largest constituent at 28.67% weight, opens Friday with cautious buyers returning. At approximately ₹615-630 — its lowest CY26 level since before the June recovery — DLF’s discount to analyst targets of ₹775 is now the widest it has been in this entire correction cycle. The stock’s Gurugram launch pipeline — DLF Privana and related projects — opens for Navratri bookings from Saturday. Whatever the rate hike has done to buyer affordability at the margin, DLF’s Gurugram projects have historically attracted buyers who absorb incremental EMI increases without deferring their purchase decisions. Tomorrow’s booking response will be the most direct available test of that resilience.
Lodha Developers opens Friday at approximately ₹1,060-1,080 — below the October 1 close of ₹1,105.60. The company’s Mumbai and Thane pipeline is positioned for Navratri with projects across multiple price points. Lodha’s Q2 FY27 presales disclosure — expected imminently — remains the sector’s most anticipated fundamental data point. A strong Q2 FY27 figure from Lodha, arriving through the weekend alongside the first Navratri booking reports, would be the most complete demand confirmation the sector could receive in a single 48-hour window.
Godrej Properties, Prestige Estates Projects, Sobha, Phoenix Mills, Brigade Enterprises, Anant Raj, Aditya Birla Real Estate, and Oberoi Realty all open Friday with a positive to flat bias — the sector recovering modestly from Thursday’s rate-hike-driven selldown without yet making a decisive move in either direction. The decisive move will come from the data — and that data begins tomorrow.
Oil softening in the Asian trading session on Friday is a quiet but specific positive for the sector’s construction cost story. Crude easing below $102 — where it had been stuck through Thursday’s session — reduces the compounding pressure that had made the past two sessions particularly difficult: higher home loan rates for buyers and higher construction costs for developers simultaneously. Any sustained oil decline through Friday’s session would separate those two pressures and allow the market to assess the rate hike’s demand impact in isolation from the crude oil input cost story.
What Is Working
The rate hike being fully priced across two sessions — Wednesday’s 429-point Sensex fall and Thursday’s 1,045-point crash — means that Friday’s buyers are not being surprised by anything the RBI has done. The hike is known. The stance is known. The forward guidance is known. Buying realty stocks on Friday is buying them with complete information about the rate environment — which is a healthier foundation for institutional accumulation than buying them before the MPC met, in a context of uncertainty about the committee’s direction.
Navratri beginning tomorrow is the domestic demand catalyst that the sector has been preparing for through the entirety of Q2 FY27’s turbulence. The festive homebuying window that India’s residential real estate sector relies on most heavily is not a market event — it is a cultural and financial tradition that operates on its own calendar. Saturday October 10 is that calendar’s opening day for 2026. Developers from Lodha in Mumbai to DLF in Gurugram, Prestige in Bengaluru to Sobha in the NCR have prepared their launches precisely for this window. The supply side is ready. The question is how much of the demand side has been dampened by a 25 basis point rate hike arriving three days before the window opened.
The broader market bouncing 700 points removes the most damaging element of Thursday’s session for the sector — the systemic market-level selling that had dragged even fundamentally strong developer stocks to five-month lows alongside every other equity in a 1,045-point crash. Friday’s bounce allows the sector to trade on its own merits rather than being pulled down by the market’s rate-shock reaction.
DII buying at five-month low prices — the most reliable single predictor of the sector’s institutional support floor through CY26 — is expected to remain active on Friday. DIIs that have deployed capital through every macro headwind of the past seven months will find the combination of record Q2 FY27 presales expected imminently, Navratri demand beginning tomorrow, and prices at five-month lows the most compelling accumulation context the sector has offered since the June recovery began.
What Isn’t Working
The home loan rate revision is already underway. HDFC Bank, SBI, ICICI Bank, and Axis Bank are adjusting their external benchmark-linked home loan rates upward by 25 basis points in the days following Wednesday’s RBI hike. For a buyer walking into a developer’s sales office on Saturday, that rate revision is a fact — not a future concern but a present reality affecting the EMI calculation on every loan application being processed this weekend. The question is not whether the rate has gone up but whether the buyer proceeds despite it — and the answer to that question will only be known through the booking figures that begin emerging from this weekend’s launches.
The RBI’s calibrated tightening stance — with rate cuts explicitly off the table — changes the medium-term rate environment within which developers price their projects and buyers plan their finances. In the 2025 easing cycle, a buyer could reasonably expect that a floating rate home loan would become cheaper over time as the RBI continued cutting. In the current calibrated tightening cycle, that assumption is reversed — a buyer on a floating rate today should expect their rate to remain stable at best and potentially rise at next MPC meeting. That change in rate direction expectations has a psychological impact on buyer behaviour that is harder to quantify than the 25 basis point EMI change but is equally real.
Nifty Smallcap falling 0.17% on Friday — even as Sensex rises 700 points — signals that the market’s recovery is not uniform across all size segments. Smaller developer names within the sector face a more selective recovery environment than their large-cap peers. Brigade Enterprises and Anant Raj, which are the sector’s smaller constituents by market cap, may see thinner buying on Friday relative to DLF and Lodha.
What to Watch Through the Day
Navratri launches beginning tomorrow are the week’s most important forward-looking variable — and the first signals will arrive through informal channels over the weekend. Watch for any developer press release, channel check, or investor briefing through Saturday and Sunday reporting initial booking volumes from Navratri launches. The first Navratri weekend’s booking data from DLF Privana in Gurugram, Lodha projects in Mumbai and Thane, Godrej Properties’ NCR launches, and Prestige Estates’ Bengaluru pipeline will set the tone for the sector’s October narrative.
Q2 FY27 presales disclosures from Lodha Developers and DLF are expected in the coming days. A Lodha Q2 FY27 presales figure above ₹4,500 crore — or a DLF number above ₹4,000 crore — would confirm that Q2 FY27 demand absorbed the quarter’s macro turbulence and provide the fundamental baseline from which Q3 FY27’s festive season can build.
Oil’s hold below $101 through Friday’s session is the energy market checkpoint. Crude closing below $101 today — after Thursday’s above-$102 levels — would confirm that the energy market is not adding fresh pressure to a sector already dealing with a domestic rate hike. A sustained oil decline toward $97-98 over the weekend would add meaningful input cost relief to the festive season’s demand positive.
The Nifty50’s close above 22,400 today would be the week’s most important technical signal. A weekly close above 22,400 confirms that Thursday’s 22,231 low was a panic capitulation rather than a structural breakdown — and that Q3 FY27 begins from a technical floor rather than a breakdown point. Realty’s positioning into next week will be strongly influenced by where the Nifty closes today.
Friday October 9 is the market’s first attempt to move past the rate hike’s immediate shock and look toward what comes next. What comes next is Navratri. The launches are ready, the buyers have been saving, and tomorrow the festive season begins. The realty sector’s price level today — at five-month lows — will be the benchmark against which October’s booking data, presales disclosures, and festive season reports are measured. The data begins arriving tomorrow morning. And for the first time in two weeks, the market’s mood is not actively working against the sector as it waits for that data to come in.