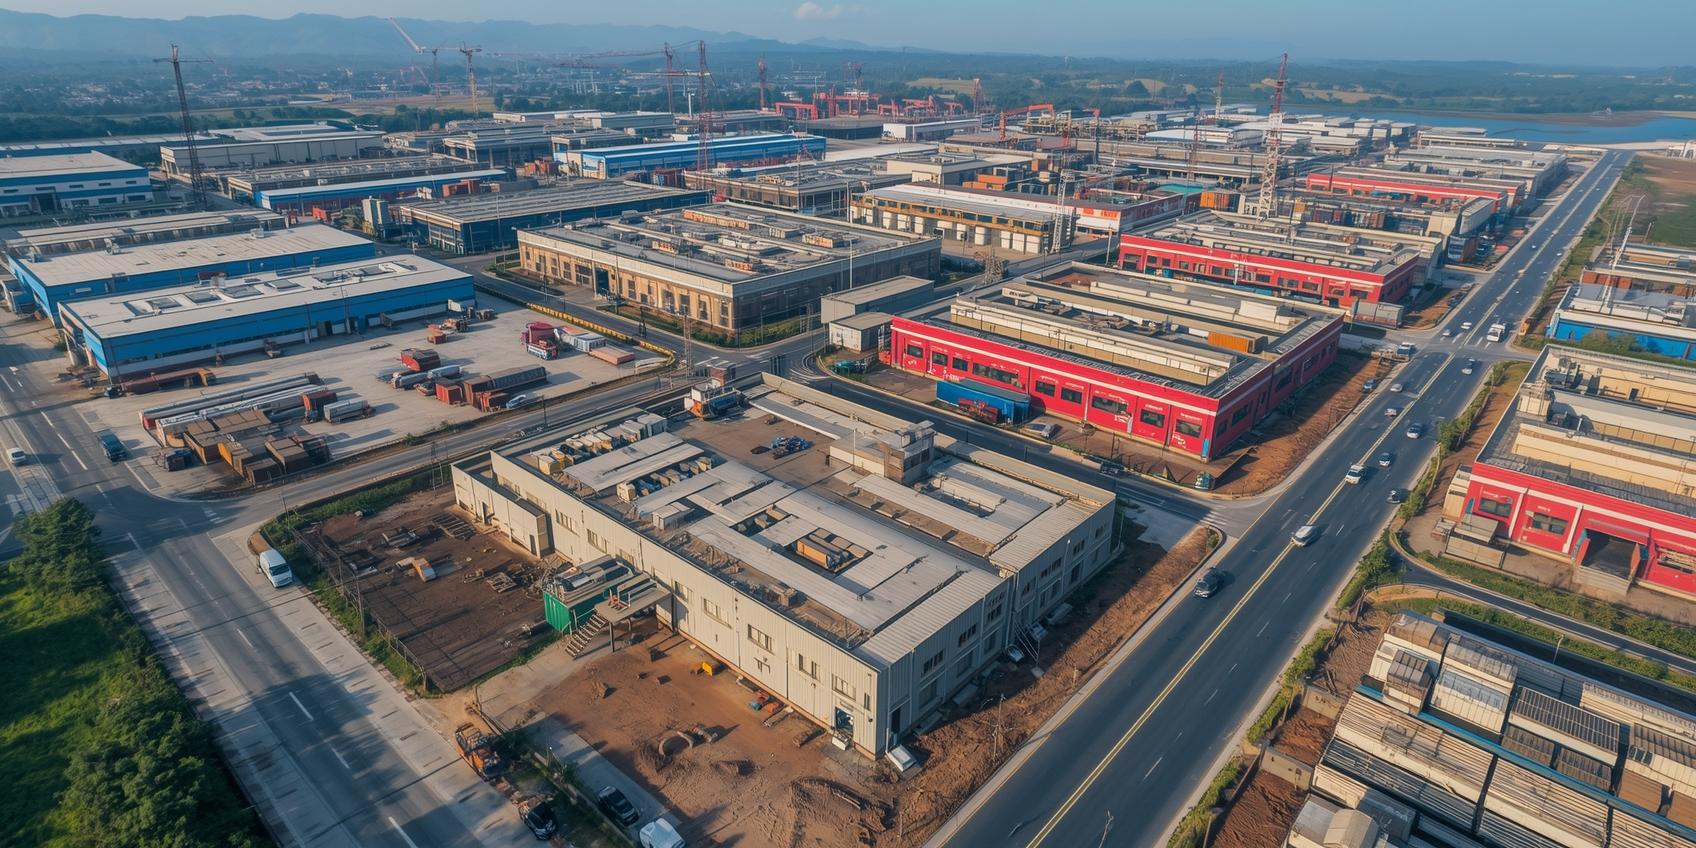
India’s warehousing and logistics sector witnessed a measured slowdown in 2025, marking a reset after hitting a post-pandemic peak in the previous year. According to Vestian Research, pan-India warehousing absorption declined to 38.7 million sq ft in 2025 from a record 44.9 million sq ft in 2024, reflecting a 14% year-on-year drop. However, the sector remains structurally strong, with leasing volumes still 84% higher than pre-COVID levels recorded in 2020.
The moderation comes after four years of aggressive capacity expansion by key occupier segments such as e-commerce, manufacturing, and third-party logistics (3PL) players. In the post-COVID phase, companies rapidly scaled up warehouse footprints to strengthen supply chains, support rising consumption, and meet faster delivery timelines. By 2025, much of this capacity had already been created, prompting occupiers to temporarily pause large-scale expansion and focus on consolidating and optimising existing networks.
Industry experts view the decline as a natural correction following an intense growth cycle rather than a sign of weakening demand. Shrinivas Rao, FRICS, CEO of Vestian, noted that the slowdown was driven by a high base effect and cautious occupier sentiment amid global uncertainty. Despite softer absorption, demand from core sectors such as e-commerce, manufacturing, and logistics remained resilient, with occupiers increasingly prioritising Grade A assets in established markets.
Mumbai continued to dominate the warehousing landscape in 2025, recording the highest absorption among the top seven cities at 15.2 million sq ft, even as leasing activity declined 18% year-on-year. The city’s share in pan-India absorption slipped marginally from 41% in 2024 to 39% in 2025. Notably, tight supply conditions pushed average rentals up by 16% to ₹21 per sq ft per month.
Pune retained its position as the second-largest warehousing market, with absorption of 6.4 million sq ft. However, this represented a sharp 51% decline from the exceptional 13.0 million sq ft recorded in 2024, indicating market normalisation. Despite lower leasing volumes, Pune emerged as the most expensive warehousing market in India, with rentals rising 22% to ₹28 per sq ft per month.
The National Capital Region (NCR) stood out with a strong rebound, as absorption jumped 38% year-on-year to 5.5 million sq ft. Its share in total absorption increased from 9% to 14%, supported by steady demand and a 4% annual rise in rentals to ₹23 per sq ft per month.
Southern markets delivered mixed performance. Hyderabad saw absorption decline 31% in 2025, with its share slipping slightly to 6%. Nevertheless, rentals increased 10% to ₹20.8 per sq ft per month, reflecting continued occupier preference for quality assets. In contrast, Bengaluru and Chennai recorded healthy growth, with absorption rising 30% and 39%, respectively, although rental values in both markets remained largely stable.
Kolkata emerged as a surprise performer, with its share in pan-India absorption tripling to 6%. Leasing volumes surged 175% year-on-year, supported by improving infrastructure and growing occupier interest, leading to a moderate 6% rise in rentals to ₹22 per sq ft per month.
Looking ahead, industry fundamentals remain favourable. Strengthening domestic consumption, improving macroeconomic stability, and easing financing conditions are expected to support demand in 2026. As per industry estimates, annual warehousing absorption is projected to rebound to 40–45 million sq ft, indicating renewed momentum for the sector after a phase of consolidation.
Also Read: Robust Investments Bolster Warehousing & Logistics Sector in 2024