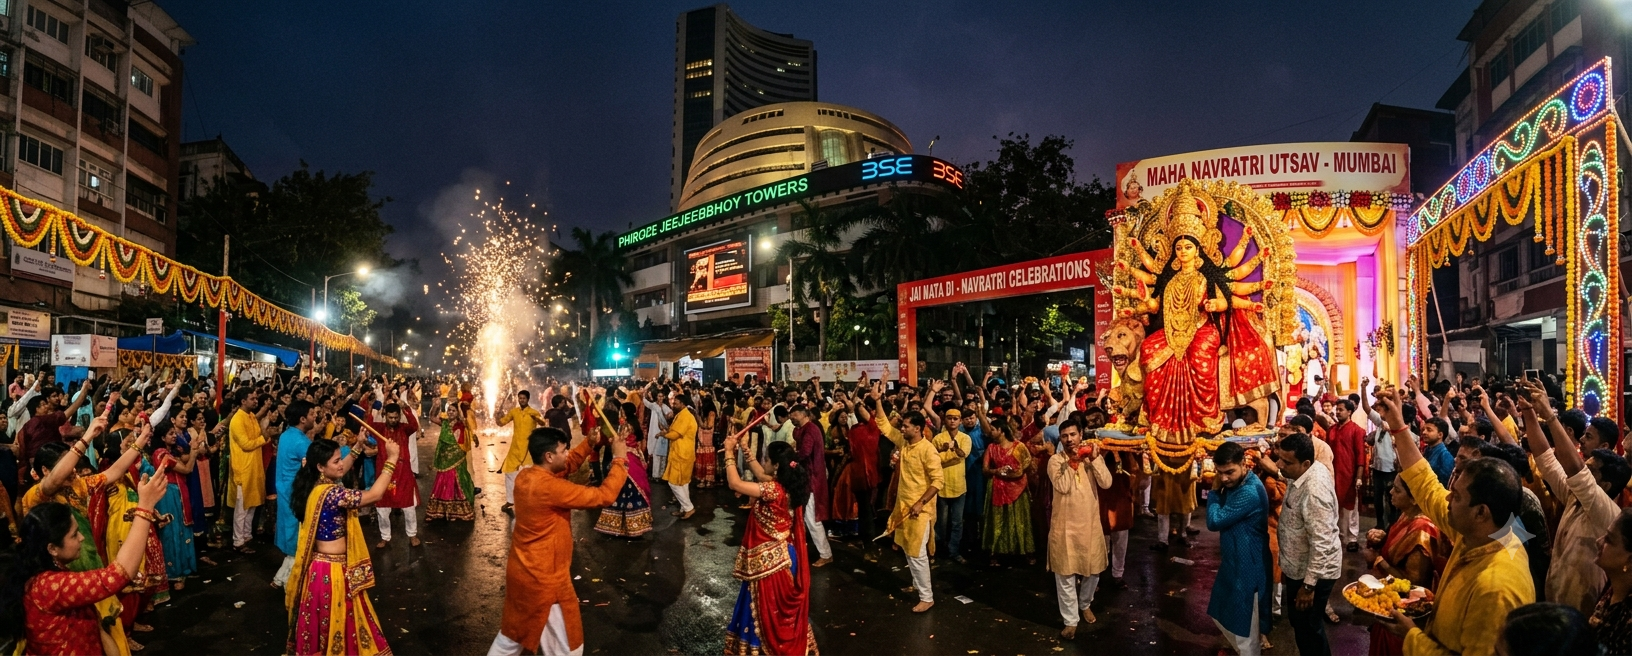
Monday October 12 has opened with two developments that directly matter to India’s listed real estate sector — and both of them are domestic. The rupee has surged 98 paise against the dollar in the morning session — one of the sharpest single-session currency moves of the year. And Navratri began yesterday, Saturday October 11, with developer sales offices across Mumbai, Pune, Gurugram, Bengaluru, and Hyderabad receiving the first festive season homebuyers of Q3 FY27. The Sensex has opened 370 points higher at 72,842. The Nifty is above 22,627. Market breadth is strongly positive — 2,120 stocks advancing against 466 declining. And realty stocks are opening Monday with the most domestically grounded positive combination the sector has received since the quarter began.
The Peg: A Rupee That Surges 98 Paise Changes the Cost of Building a Home in India
The rupee’s 98-paise single-session strengthening is not an abstract currency event. It is a construction cost event, a home loan event, and an inflation event — all three simultaneously.
Construction cost event first. India imports 85% of its crude oil and pays in dollars. A rupee that strengthens 98 paise against the dollar means that every barrel of crude India imports today costs 98 rupees less than it did on Friday. At current crude volumes, 98 paise of rupee strengthening on a sustained basis reduces India’s crude import bill by thousands of crores per month. That reduction flows through to diesel prices at Indian petrol stations — and diesel is the fuel that runs every cement truck, every construction vehicle, and every generator on every active building site in the country. When the rupee strengthens 98 paise, the diesel bill for building a 40-storey residential tower in Mumbai comes down. That cost reduction directly supports developer margins in Q3 FY27.
Home loan event second. India’s home loan market is priced partly on the basis of external benchmark lending rates — which are linked to the repo rate and to broader market rate expectations. A rupee that strengthens sharply signals to bond markets that India’s inflation trajectory may be improving faster than the worst-case scenarios had assumed. A strengthening rupee reduces the cost of crude imports in local currency terms, which reduces fuel and transport inflation, which gives the RBI’s calibrated tightening stance more flexibility to pause rather than hike again at the December MPC meeting. For a homebuyer who took a floating rate loan after the October 7 rate hike, a rupee that is strengthening 98 paise is the first signal that the rate cycle may be closer to its peak than Governor Malhotra’s press conference had implied.
Inflation event third. A rupee at 98 paise stronger means that every imported good India buys — from crude oil to edible oil to fertilisers — costs less in rupee terms than it did on Friday. That import cost reduction flows into India’s CPI trajectory, which is the single most important variable determining whether the RBI hikes again in December or pauses. If September’s CPI — due in mid-October — shows improvement on the back of a stronger rupee and softer crude, the RBI has the data it needs to pause the tightening cycle. A pause in December would be the most important domestic monetary policy positive the sector could receive in Q3 FY27.
How Realty Stocks Are Opening
The Nifty Realty index enters Monday from the Friday close of approximately 820-830 — having recovered through Friday’s 1.30% Nifty advance from the five-month lows reached during Thursday’s post-rate-hike crash. Monday’s positive open adds to that recovery.
DLF, the index’s largest constituent at 28.67% weight, opens Monday with the most conviction buying it has attracted since before the RBI rate hike announcement. The stock at approximately ₹625-645 — still approximately 17-20% below analyst targets of ₹775 — is receiving buyers who see the rupee’s 98-paise strengthening as the input cost signal they had been waiting for to confirm that the worst of the Q3 FY27 margin pressure has passed. DLF’s Gurugram launch pipeline — which opened for Navratri bookings on Saturday — is the domestic demand catalyst that is building in parallel with the rupee’s positive macro signal.
Lodha Developers opens Monday with buyers who are simultaneously watching two positive signals: the rupee strengthening that reduces Mumbai’s construction cost environment, and the first Navratri weekend’s booking activity from the company’s Mumbai and Thane project portfolio. Lodha’s Q2 FY27 presales disclosure — expected imminently — remains the sector’s most anticipated fundamental data point. Any Q2 FY27 figure above ₹4,500 crore, arriving alongside the rupee’s strong Monday signal, would give institutional investors the complete picture — macro positive and fundamental positive arriving in the same week.
Godrej Properties opens Monday with its most geographically diverse festive demand exposure across NCR, Mumbai, Bengaluru, and Pune all engaged simultaneously. Prestige Estates Projects, whose Bengaluru and Hyderabad markets are among the most active festive season homebuying cities in the country, opens with buying that reflects both the macro positive from the rupee and the demand positive from Navratri’s opening weekend. Sobha, Phoenix Mills, Brigade Enterprises, Anant Raj, Aditya Birla Real Estate, and Oberoi Realty all open Monday with a positive tone — the sector’s most uniformly constructive opening since the first week of October.
HCL Technologies reporting Q2 FY27 results today is the earnings season’s most directly realty-relevant tech company disclosure. HCL Tech’s Q2 results will provide the employment and salary confidence signal for Bengaluru, Hyderabad, and Noida — three cities where Prestige Estates, Brigade Enterprises, and Sobha earn the most consistent residential booking volumes from IT sector employees. A strong HCL Tech result today would be the sector’s most relevant earnings catalyst of the week.
What Is Working
The rupee’s 98-paise single-session surge is Monday’s most important domestic positive — and it is measurably different from the generic “rupee strengthens” headline that markets see regularly. A 98-paise single-session move is significant. It signals that a specific positive development has changed the currency market’s assessment of India’s macro trajectory materially rather than at the margin. The most likely driver is a combination of crude oil easing and a weekend Iran diplomatic signal that has reduced the geopolitical risk premium embedded in the rupee’s exchange rate. Whatever the specific trigger, a rupee that moves 98 paise in a single session is a rupee that is restoring India’s import cost advantage — and that restoration is the most direct macro positive the realty sector’s construction economics can receive.
Navratri having opened on Saturday October 11 — with the festive homebuying window now live — is the domestic demand catalyst the sector has been preparing for through an entire quarter of macro turbulence. The first weekend of Navratri bookings from developer sales offices across India will begin reaching the market through Monday’s session — informal channel checks, developer social media updates, and press releases from project launches will provide the first real-time demand data of Q3 FY27. That data — when it arrives — will tell institutional investors more about the sector’s actual demand resilience than any macro indicator can.
Market breadth of 2,120 advancing to 466 declining — a ratio of more than 4.5 to 1 — is the internal market signal that Monday’s positive open is broad-based rather than concentrated in a handful of heavyweights. For the realty sector, which benefits most from institutional risk-taking across multiple size segments, a market where small and mid-cap stocks are advancing alongside large-caps — Nifty Auto up 1.2%, Nifty Smallcap up 1.04% — is the most constructive breadth environment the sector can operate in.
Friday October 9’s 879-point Sensex surge — which closed the previous week on a strongly positive note — has given Monday’s session a technical foundation to build on. A market that enters Monday’s open above its previous Friday close — Sensex at 72,842 versus Friday’s 72,472 close — is a market that has not given back the week-end’s recovery overnight. That sustained recovery is the technical positive that allows Monday’s macro and demand-side catalysts to compound rather than being offset by a deteriorating chart.
What Isn’t Working
Crude oil remaining significantly above pre-war levels — despite Monday’s marginal pullback — is the input cost reality that the rupee’s 98-paise surge partially offsets but does not eliminate. The effective crude cost for India in rupee terms is lower on Monday morning than on Friday — and that is a genuine positive. But the absolute level of crude, still well above the $72-75 range at which the sector had been performing best, means that construction cost pressures have not fully reversed. The margin recovery that the sector needs for a sustained re-rating toward its 1,009.30 CY26 high requires crude to fall toward $85-90 and sustain there — not just to soften marginally from elevated levels.
US Treasury yields remaining elevated and the US dollar staying strong — cited as a caution factor in Monday’s pre-open analysis — are the external financial variables that keep institutional positioning cautious even on a positive domestic morning. Elevated US yields mean that global capital still has a high-yielding risk-free alternative to emerging market equities, and a strong dollar continues to create FII outflow pressure on Indian equities at the margin. The rupee’s 98-paise surge is a domestic positive that partially counteracts those pressures — but until US yields peak and begin declining, the structural FII selling pressure on Indian equities does not fully reverse.
PSU bank shares weighing on the Sensex through Monday’s intraday session — with the index pulling off its morning highs as IT, FMCG, and bank shares weighed — is a reminder that Monday’s positive open has not translated into uniform buying across all sectors. The market remains selective in its recovery, and realty stocks must demonstrate their own demand-side positive through Navratri booking data rather than relying entirely on market-level lift.
The RBI’s repo rate at 5.50% and calibrated tightening stance are unchanged by Monday’s rupee surge or crude easing. Home loan rates are rising across India’s banking system in response to Wednesday’s hike. The first Navratri weekend’s buyer responses — how many buyers absorbed the higher EMI and booked anyway, and how many deferred to watch December’s MPC meeting — will be the demand-side answer to the RBI’s rate decision. That answer is beginning to arrive through Monday’s channel checks and developer updates, but will only be fully visible in the formal Q2 FY27 presales disclosures and Navratri booking reports that come through this week.
What to Watch Through the Day
Navratri booking reports from listed developers are Monday’s most important domestic catalyst to watch. Any press release, regulatory filing, or investor briefing from Lodha Developers, DLF, Godrej Properties, Prestige Estates, or Sobha confirming initial Navratri launch booking volumes would be the sector’s first direct Q3 FY27 demand data point. A strong first-weekend booking figure — comparable to previous Navratri opening weekends — would confirm that structural demand has absorbed the 25 basis point rate hike and that the festive season’s demand wave is building as expected.
HCL Technologies’ Q2 FY27 results today are the earnings season’s most realty-relevant tech disclosure. HCL Tech’s revenue growth, hiring intentions, and employee count trajectory will signal the employment sentiment in Bengaluru, Hyderabad, and Noida that directly determines residential demand in those cities through the festive season.
The rupee’s hold above its morning surge levels through the full session is the currency variable to watch. A rupee that sustains its 98-paise strengthening through 3:30 PM confirms that the move is fundamental rather than intraday noise. A rupee that gives back its gains by afternoon would suggest that the morning’s move was positioning-driven and less durable than it appears at open.
The Nifty50’s hold above 22,600 is Monday’s primary technical checkpoint. A close above 22,600 would confirm that the market has reclaimed the level from which Thursday’s rate-hike-driven crash had dislodged it and that Q3 FY27’s recovery is building on a stable technical foundation heading into the festive season’s peak weeks.
Monday October 12 opens the first full week of Navratri — and does so with the rupee’s most significant single-session strengthening of recent months, a market that has bounced back from Thursday’s crash across two consecutive positive sessions, and a festive homebuying season that was open for business from Saturday. The sector’s story this week is a domestic one — how many homebuyers walked into sales offices over the weekend, and how many of them signed booking cheques despite knowing that home loan rates have just risen by 25 basis points. By Friday, that answer will have begun arriving through developer disclosures, channel checks, and the Q2 FY27 presales figures that the sector’s most anticipated fundamental data releases will deliver. Today is the week’s opening chapter.
Also Read: Realty Stocks Open Carefully as Traders Brace for Three-Day Break After a Punishing Quarter