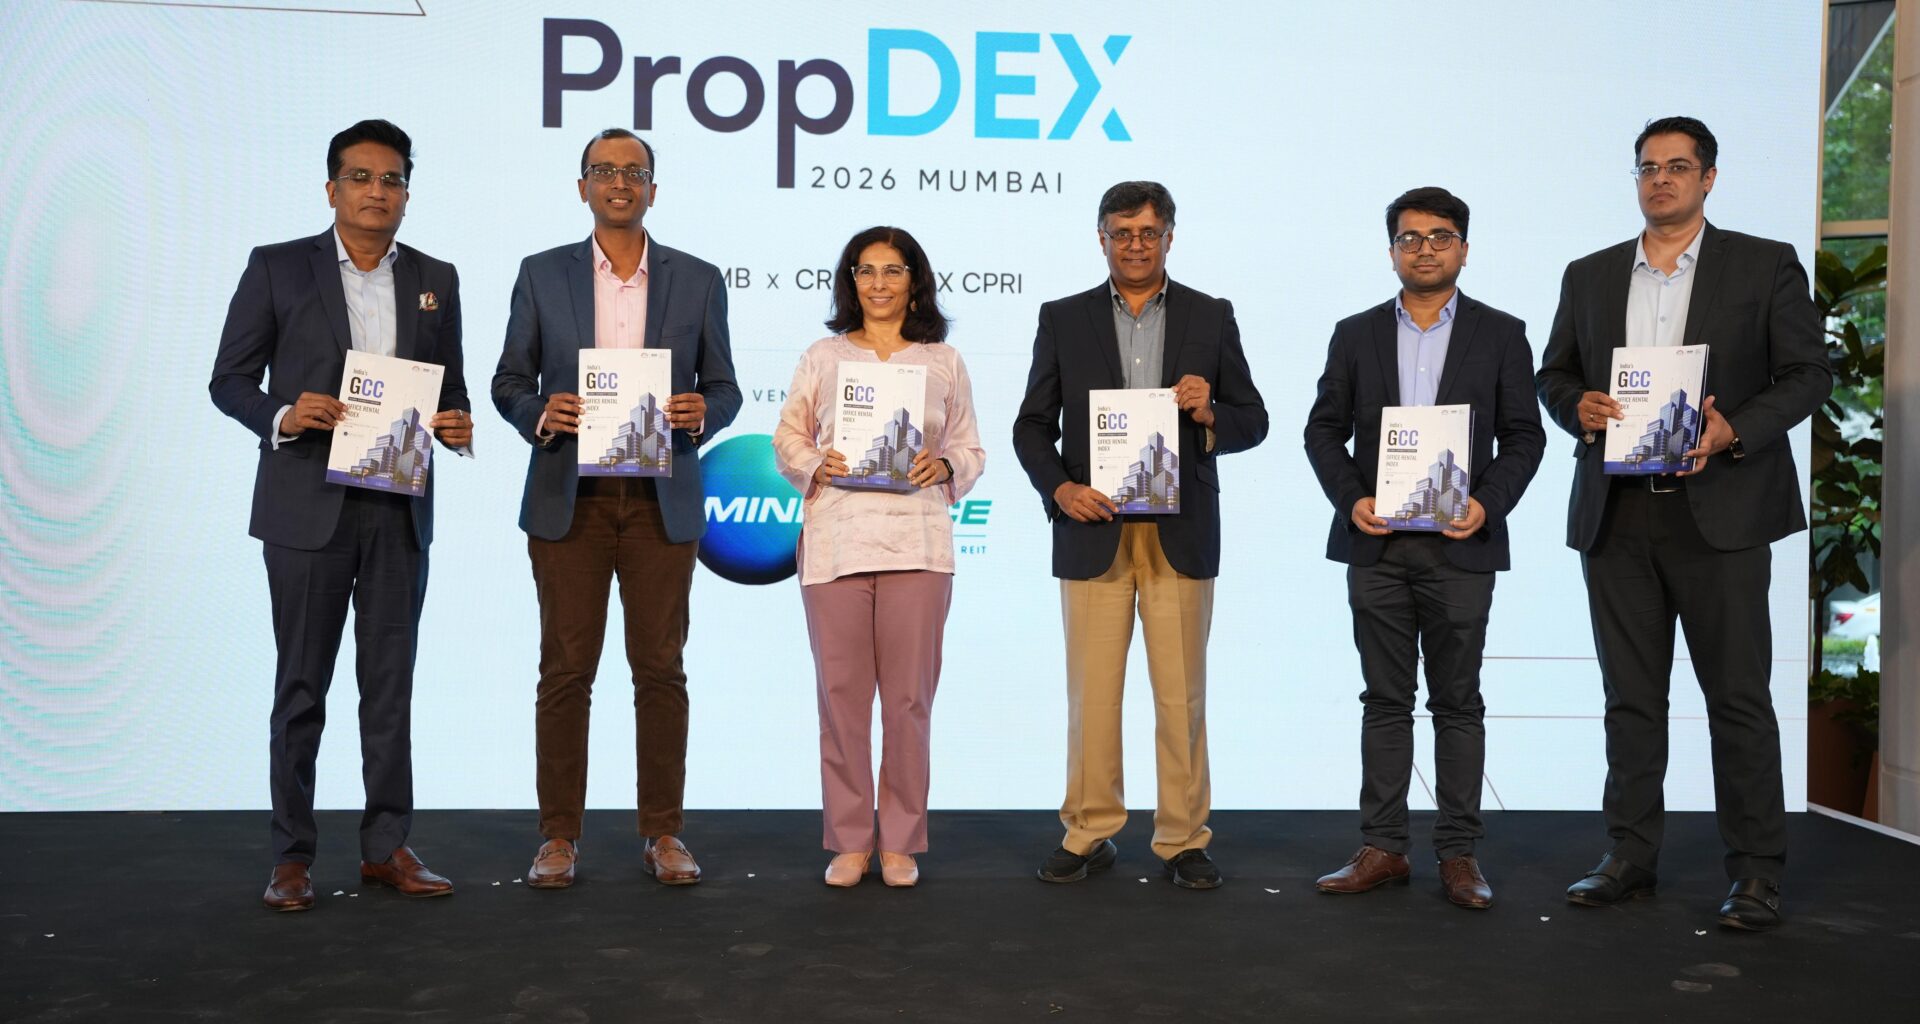
The first edition of the IIMB-CRE Matrix GCC Commercial Property Rental Index (CPRI) for Q1 CY’26 reveals a nuanced shift in India’s Global Capability Centre office market. While GCC occupiers once commanded a clear rental premium, the broader commercial real estate market has now largely caught up, signalling a gradual broadening of demand drivers across Grade A and A+ office spaces.
Pan-India, the GCC CPRI stood at 165.3 (base Q1 CY’14 = 100), slipping 0.5% quarter-on-quarter and 5.8% year-on-year, though it still posted a modest 0.9% three-year CAGR. In contrast, the all-occupier CPRI rose to 165.0, gaining 1.1% QoQ and 2.9% YoY with a stronger 4.8% three-year CAGR. The narrowing spread indicates that GCC-specific demand, while still robust in select hubs, is no longer the sole engine of rental growth; wider occupier interest is now supporting the market.
Hyderabad emerged as India’s strongest GCC rental market with a CPRI of 212.1, up 5.4% YoY and 4.4% over three years. The city also recorded the widest GCC premium — GCCs paid 15% above market rents and 10% above passing rents. Hitec City remained the standout micro-market, driving consistent appreciation and attracting large-format leases, including Novartis Healthcare’s 8.66 lakh sq ft commitment and Qualcomm’s 3.89 lakh sq ft deal in Madhapur.
Pune followed closely with a GCC CPRI of 210.7, maintaining a high base after strong prior compounding. It posted the widest GCC-to-rental premium among major cities at +16.3% (210.7 vs 181.2 all-occupier CPRI). The market has entered a consolidation phase after rapid growth, with rents now plateauing but still showing a healthy 20% premium over non-GCC rentals. North-East Pune anchored leasing activity, supported by long-tenure deals such as Maersk’s 1.93 lakh sq ft and UBS’s 1.43 lakh sq ft commitments.
Bengaluru, India’s largest GCC market by occupied stock (57% GCC share), recorded a CPRI of 190.0. Growth has slowed to +1.6% over three years, yet the city continues to command significant premiums, with GCC market rents notably higher than non-GCC levels. Whitefield (286.9) and South Bengaluru (257.9) led micro-market performance, while Outer Ring Road remained the volume driver despite some large-block transactions moderating average rental growth.
In the Mumbai Metropolitan Region, the story was one of convergence and selective strength. Mumbai’s GCC CPRI reached 149.0, nearly matching the broader CPRI at 144.7 — the tightest positive spread among premium cities. This suggests GCC pricing has effectively become the market benchmark rather than a premium paid to access it. Central Suburbs posted a strong GCC CPRI of 217.0 with robust three-year growth, while Navi Mumbai (170.7) and Thane (182.3) delivered healthy YoY gains of 6.3% and 6.5% respectively, pointing to rising GCC interest in MMR’s suburban corridors.
At the other end, Chennai’s GCC CPRI fell sharply to 80.6 (-37.1% YoY), while Gurgaon and Noida also recorded deep corrections. These declines reflect new GCC leases being signed at rates materially below levels seen one to three years ago, a clear reversal of earlier momentum.
The report underscores that GCCs continue to favour quality assets with larger deal sizes, longer tenures (often 60–120 months), and sharper specifications. They remain key anchors for macro-markets such as Whitefield, Hitec City, Central Mumbai suburbs, and North-East Pune. However, the pan-India cooling in GCC rents alongside rising broader-market rents points to a maturing, more balanced commercial office landscape where location quality and infrastructure readiness matter more than ever.
For developers and investors, the findings highlight clear opportunities in GCC-ready Grade A/A+ projects in Hyderabad, Pune, and select Bengaluru and Mumbai micro-markets, even as aggregate growth moderates.
Also Read: GCC Policy Impact on Residential Real Estate in Bengaluru