There are mornings when the market surprises itself. Thursday September 18 is one of them. The US Federal Reserve delivered its 25 basis point rate hike on Wednesday — the outcome that had been weighing on Indian equities for three weeks, compressing the Nifty Realty index by 9.33% across seven consecutive sessions and pushing the Sensex to its lowest since June 2026. And yet, when the hike actually arrived, the Indian market did something unexpected. It bounced. The Nifty recovered from an intraday low of 23,193 to touch 23,325. The Bank Nifty climbed from 56,072 to a day high of 56,570. DIIs stepped in with ₹3,900 crore of net purchases. The worst was already in the price — and across Mumbai, Pune, Thane, and every Maharashtra city where Ganesh Chaturthi pandals are still standing, the homebuying mood that this festival quietly generates every year is now the force the market is turning toward.
The Peg: The Fed Did What It Said It Would. Ganesh Chaturthi Is Doing What It Always Does.
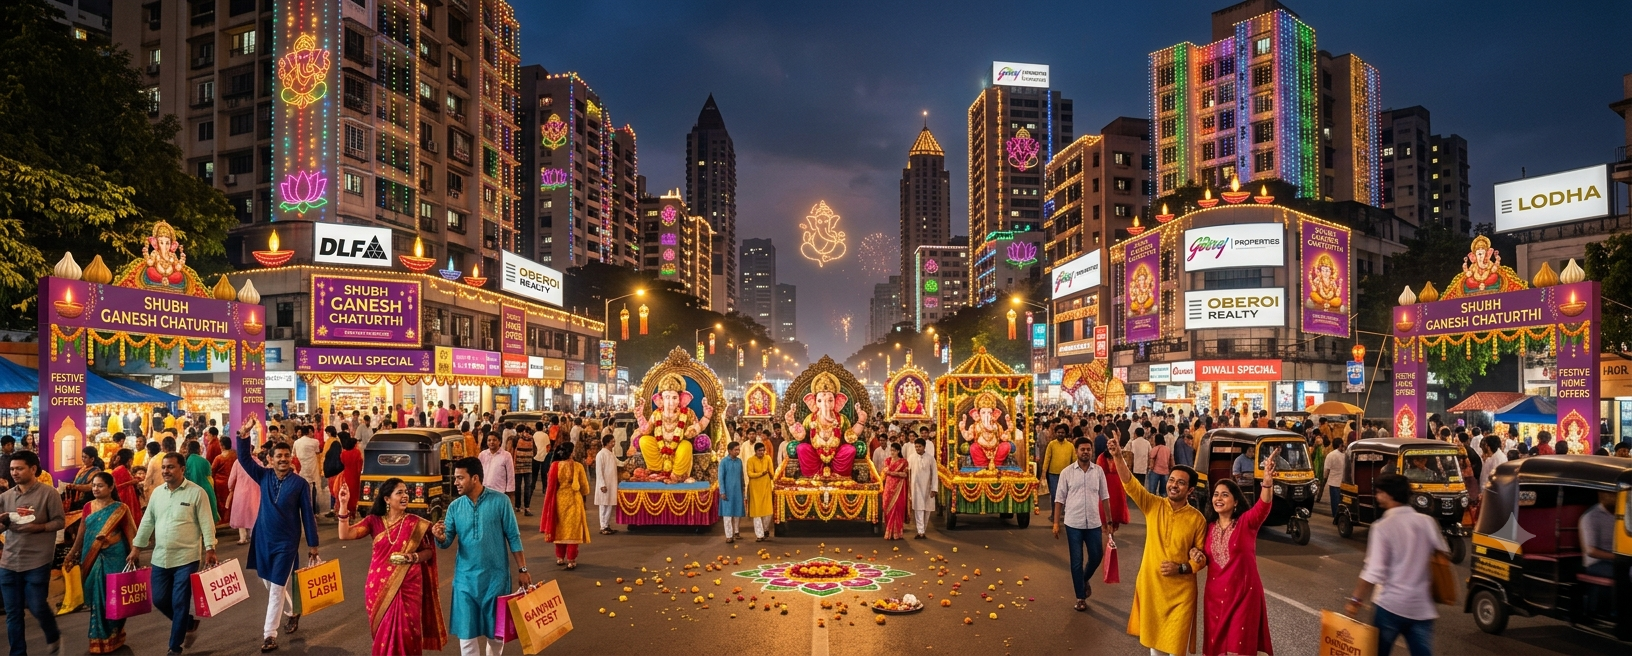
Ganesh Chaturthi is not just a festival in Maharashtra’s real estate calendar. It is a sentiment reset. The ten days of Ganapati — celebrated with particular intensity in Mumbai, Pune, and Nashik — are among the most auspicious in the Marathi homebuying tradition. Property registrations in Maharashtra consistently show a pattern of elevated transaction volumes in the week following Ganesh Chaturthi, as families that have celebrated together, discussed their aspirations together, and visited model apartments during the festive period convert that positive sentiment into signed agreements and paid tokens. Developers know this. Every major Maharashtra-focused developer — Lodha Developers, Oberoi Realty, Godrej Properties, Prestige Estates, and Rustomjee among others — has calibrated its September launch pipeline to the Ganesh Chaturthi window.
That domestic demand reality is what gives Thursday’s market open its most important characteristic. The Fed’s 25 basis point hike — with 16 of 18 policymakers signalling at least one more hike by year-end — is a genuine macro negative for rate-sensitive sectors. It strengthens the dollar, puts the rupee under pressure at ₹96.01, keeps crude import costs elevated at above $108 per barrel, and complicates the RBI’s October MPC meeting calculus. None of that is good news for the sector in isolation.
But the market had been selling this outcome for three weeks. The hike has arrived and been delivered. What replaces it — in the domestic demand story — is a Maharashtra that is in the final days of Ganesh Chaturthi, a Mumbai Metropolitan Region where homebuyer sentiment is at its annual September peak, and a listed developer universe that has the strongest festive launch pipeline in years ready to engage that sentiment.
How Realty Stocks Are Opening
The Nifty Realty index enters Thursday from the position Wednesday’s intraday recovery left it — having absorbed the Fed hike, bounced from session lows, and closed with a partial recovery that the broader market’s DII-driven buying support had made possible. The rupee opened at ₹96.01 — weaker than the ₹94.45 two-month high that the FCNRB deposit surge had briefly delivered, but significantly less alarming than the ₹97-plus levels the most bearish post-hike scenarios had been pricing.
DLF, the Nifty Realty index’s largest constituent at a 26.86% weight, opens Thursday with measured institutional buying. The company’s Gurugram project pipeline — including the DLF Privana series that has generated some of the most dramatic single-session sellout events in the sector’s recent history — is actively generating booking interest even through September’s macro turbulence. At current levels, DLF’s discount to analyst targets of ₹775 remains approximately 14-17% — the catch-up trade that has been the sector’s most discussed institutional positioning story through the entire CY26 recovery cycle.
Godrej Properties opens Thursday with the sector’s most ambitious growth story still intact. The company’s ₹27,000 crore FY27 presales target and ₹2 lakh crore gross development value pipeline span Mumbai, Bengaluru, Pune, and the NCR — four of India’s most active residential markets during the festive season. The Ganesh Chaturthi window is particularly relevant for Godrej Properties’ Mumbai pipeline, where the company has active projects across Vikhroli, Bandra, Kandivali, and the western suburbs.
Lodha Developers, whose record ₹5,620 crore Q1 FY27 presales remain the sector’s most powerful fundamental anchor, opens Thursday as the name where institutional conviction is most deeply embedded. Lodha’s Mumbai and Thane presence makes it the most direct beneficiary of the Ganesh Chaturthi homebuying sentiment — the company’s Palava township and its premium Mumbai projects have consistently shown above-average booking activity through the Maharashtra festive season. Prestige Estates Projects, Sobha, Phoenix Mills, Brigade Enterprises, Anant Raj, Aditya Birla Real Estate, and Oberoi Realty all open Thursday with a cautious positive to flat bias — the sector in recovery mode after three weeks of macro-driven selling.
Oberoi Realty opens Thursday carrying the specific positive of its luxury Mumbai positioning — the Worli and Mulund projects that sit at the premium end of exactly the demand segment that Ganesh Chaturthi’s sentiment most powerfully activates. The company’s Three Sixty North Gurugram court restraint order remains an unresolved legal overhang, but within the broader Maharashtra festive demand context, the stock’s Mumbai luxury exposure is the more relevant frame for Thursday’s institutional positioning.
The NSE IPO — open for subscription today alongside six other listings — is absorbing significant retail and institutional attention simultaneously. The NSE’s own listing is one of the most anticipated public offerings in Indian financial market history, and its presence on the same morning as the sector’s post-Fed recovery open creates a specific liquidity dynamic: some retail and HNI money that would otherwise flow into secondary market realty names is today going into IPO subscriptions. This is a temporary diversion rather than a fundamental negative.
What Is Working
The Fed hike being delivered and the market having survived it — bouncing intraday rather than collapsing further — is Thursday’s most important macro positive. Sell the rumour, buy the fact. The rumour of a Fed hike had been sold through seven sessions of Nifty Realty losses and a Sensex that reached its June 2026 lows. The fact has now been delivered. The uncertainty component — which is in many ways more damaging to markets than the known bad news itself — has been removed. Institutional investors can now price the known rather than the feared. The next Fed meeting is in November, six weeks away. That six-week window is precisely the festive season period in which India’s residential real estate sector generates its most significant annual bookings volume.
DII buying of ₹3,900 crore on Wednesday is the structural floor signal that has not wavered through seven months of Iran conflict, crude above $100, and now a Fed rate hike. Domestic institutional investors that deploy ₹3,900 crore on the day of a Fed hike are making an unambiguous statement about the relative importance they place on India’s domestic growth story versus the global rate cycle. That conviction — expressed consistently through every macro headwind of CY26 — is the most reliable single indicator the sector has of its institutional demand floor.
Ganesh Chaturthi’s homebuying sentiment across Maharashtra is the domestic positive that no central bank rate decision can cancel. Developers report that Maharashtra’s festive season window — Ganesh Chaturthi through Diwali — accounts for a disproportionate share of annual booking volumes in Mumbai, Pune, Thane, and Nashik. The cultural embeddedness of property purchase decisions in this festive period means that homebuyers who have been saving, planning, and visiting project sites through August and September will convert their intentions into transactions through the festive window regardless of what the FOMC’s dot plot says.
FCNRB deposits at over $120 billion continue to provide the rupee with a buffer against the dollar’s post-hike strengthening. The rupee at ₹96.01 — while weaker than the festive season’s most optimistic assumptions — is being partially supported by the FCNRB inflow buffer that the RBI has been managing. That buffer means the rupee’s weakness is measured rather than precipitous, and the effective crude cost increase in rupee terms is contained rather than catastrophic.
What Isn’t Working
The Fed’s forward guidance — 16 of 18 policymakers expecting at least one more hike by year-end — is the forward shadow that will hang over rate-sensitive sectors through November. If the next Fed hike arrives in November, the RBI’s October MPC meeting will take place in the context of a global rate cycle that is still tightening. India’s August CPI at 4.82% — the second consecutive month above the RBI’s 4% target — makes a rate hold from the RBI increasingly difficult to justify to a committee that has been explicitly watching the inflation trajectory since June.
The rupee at ₹96.01 — weaker than the ₹94.45 level the FCNRB surge had briefly anchored it at — means that India’s crude import cost in rupee terms is higher than the month’s most optimistic assumptions had priced. At $108 crude and ₹96.01 per dollar, the effective rupee cost of India’s crude imports is at the highest level of CY26. Every construction site in India running on diesel, every cement truck on a highway, every steel delivery on a national road is paying the combined cost of dollar crude and rupee weakness simultaneously.
The NSE IPO’s liquidity absorption effect — while temporary — will create thinner secondary market volumes in realty names through Thursday. Thin volumes amplify intraday volatility, meaning that any negative development during the session could produce larger-than-normal price moves in individual stocks. Investors holding realty positions through Thursday should be aware of the volume dynamic the IPO subscription window creates.
Wall Street ending lower after initially gaining on the Fed decision — as investors processed the forward guidance for further tightening — means that global risk appetite has not fully recovered from the hike’s delivery. Asian markets remain mixed on Thursday. FII selling of approximately ₹2,000 crore on Wednesday, combined with the dollar at a seven-week high, means that global institutional money is not yet positioned for an aggressive India re-entry.
What to Watch Through the Day
Maharashtra property registration data through the Ganesh Chaturthi window is the sector’s most important domestic demand signal to track over the next few days. Any state government or industry body report showing elevated registration volumes in Mumbai’s Sub-Registrar offices through the Chaturthi period would provide direct quantitative evidence that the festive demand catalyst is delivering what the sector’s fundamentals have been promising.
Festive season launch announcements are Thursday’s most immediate company-specific catalysts. Any formal launch notification from Lodha Developers, Godrej Properties, Oberoi Realty, or Prestige Estates — with booking figures attached — will provide the independent demand signal the sector needs to demonstrate that its fundamental story is larger than any macro headwind. Watch for regulatory filings, company press releases, and project booking disclosures through Thursday’s session.
The rupee’s stabilisation at ₹96.00-96.50 through Thursday’s session is the currency market signal that most directly validates whether the post-Fed rupee weakness is being contained or escalating. A rupee that holds within that range signals that the RBI and the FCNRB buffer are managing the post-hike currency adjustment. A rupee that weakens past ₹97 would signal more serious pressure that accelerates the October RBI rate decision in the hawkish direction.
Crude oil holding below $109 through Thursday’s session is the energy market containment signal for the sector. The dollar’s post-hike strengthening could put upward pressure on crude through the commodity markets’ inverse dollar relationship, but the global demand destruction effect of higher rates should partially offset that. Brent staying below $109 would preserve the sector’s construction cost story at manageable rather than crisis levels.
Brigade Enterprises’ Q1 FY27 presales — the sector’s most anticipated remaining undisclosed data point across the entire presales season — remain the potential catalyst that could arrive at any moment through Thursday. A strong Brigade presales number arriving on a post-Fed Thursday morning, during Ganesh Chaturthi week, would be the sector’s most powerful combined statement of the CY26 story: demand is structural, bookings are real, and no rate hike cycle cancels the aspiration of a middle-class Indian family to own a home during the most auspicious season of the year.
Thursday September 18 is the morning after the worst feared macro event arrived and was absorbed. The Fed hiked, the Nifty bounced, DIIs bought ₹3,900 crore, and across Maharashtra the last days of Ganesh Chaturthi are doing what they do every September — building the homebuying sentiment that no dot plot can displace. The realty sector’s three-week story of macro-driven selling is giving way to a festive season story of demand-driven bookings. The transition is happening now. Thursday is one of the first mornings where the Ganesh Chaturthi energy on the streets of Mumbai is a more relevant indicator for listed developer stocks than the Federal Reserve’s median rate projection for year-end.
Also Read: Realty Stocks Bounce Back at Open as Nifty Recovers